

How a communications technology company increased commercial credit-line utilisation by 100%
At a glance
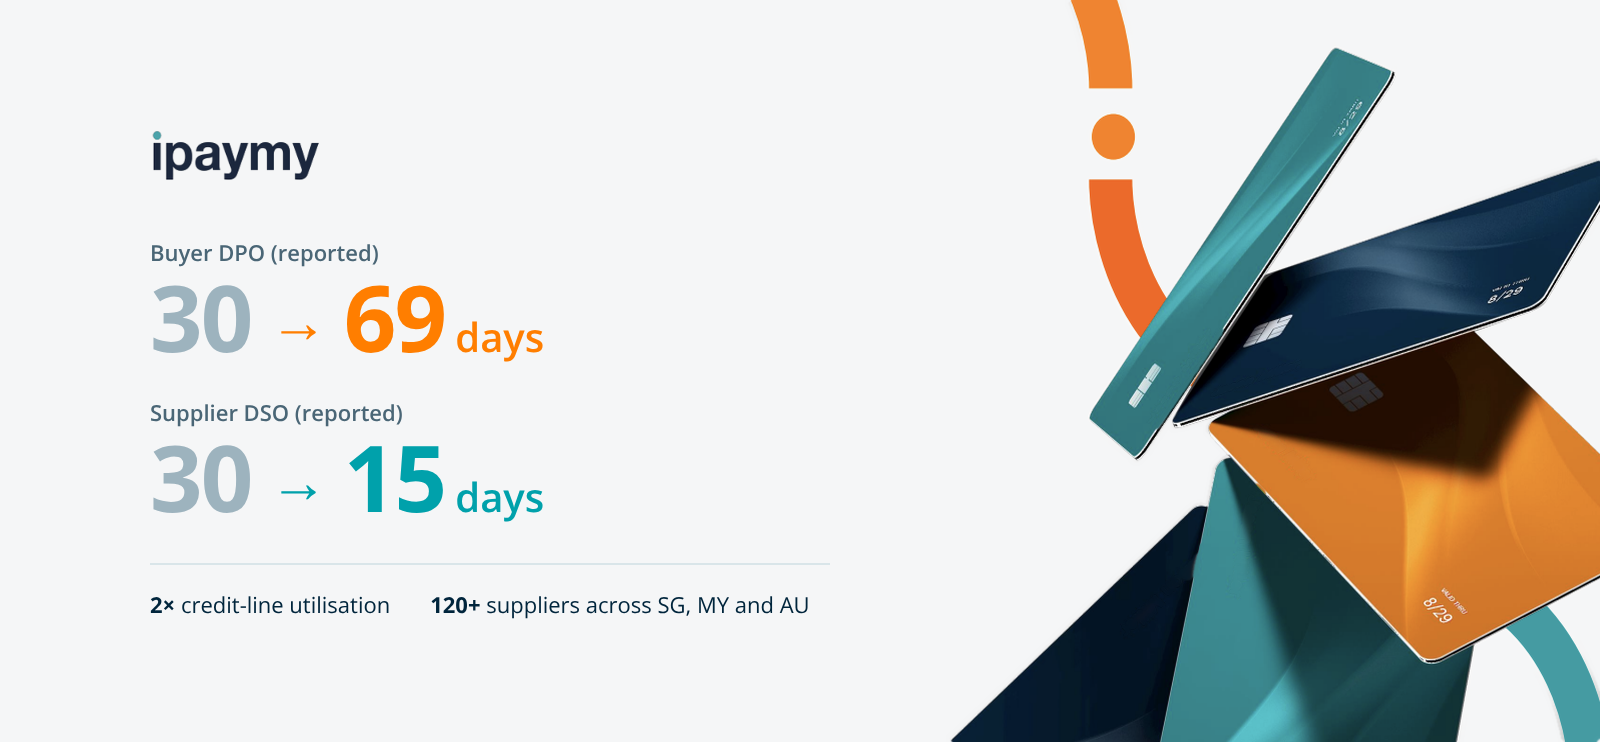
A supplier payment programme increased utilisation of the company’s commercial credit line by 100%
The communications technology company worked with ipaymy and its commercial card issuer to onboard more than 120 suppliers across Singapore, Malaysia and Australia. The programme used a supplier-funded model, with the service fee framed as an early-payment discount. Suppliers enrolled digitally, received payment notifications online and continued receiving funds in their bank accounts.
The challenge
A global communications technology solutions provider wanted to improve how it used commercial cards for business-to-business payments across Asia Pacific.
The company already used purchasing cards, but fewer than 10% of its approved suppliers accepted cards. This limited the value the company could realise from its existing commercial credit line.
The company needed a way to broaden supplier participation without requiring suppliers to introduce card acceptance or disrupting their established payment processes.
The solution
The company worked with ipaymy and its commercial card issuer to deploy a supplier payment programme across Singapore, Malaysia and Australia.
More than 120 suppliers were onboarded through a one-time digital enrolment process. The programme used a supplier-funded model in which the service fee was framed as an early-payment discount. Participating suppliers received payment notifications digitally and continued receiving funds in their bank accounts.
For this implementation, the programme did not require integration with the company’s procurement or financial systems.

How the supplier payment programme worked
Eligible suppliers were identified.
Suppliers enrolled digitally.
The buyer made approved supplier payments by card
ipaymy processed the transactions
Suppliers received funds and notifications.
The outcome
The programme expanded the company’s ability to use its commercial credit line across its supplier base while offering participating suppliers an earlier-payment option.
- Utilisation of the commercial credit line increased by 100%.
- More than 120 suppliers were onboarded across Singapore, Malaysia and Australia.
- The buyer’s reported days payable outstanding increased from 30 to 69 days.
- Participating suppliers’ reported days sales outstanding reduced from 30 to 15 days.
- Payment notifications and supplier enrolment were handled digitally.
- No integration with procurement or financial systems was required for this implementation.
Why the approach worked
The programme gave both sides a reason to participate. The buyer could use more of its existing commercial credit line, while suppliers could choose an earlier-payment arrangement and continue receiving funds in their bank accounts.
Digital enrolment and payment notifications reduced the operational effort needed to add suppliers. The collaboration between the company, its issuer and ipaymy also allowed the payment model to operate without replacing the company’s underlying procurement or financial systems.
The result greater card utilisation without requiring suppliers to accept cards
The company moved from limited supplier card acceptance to a broader supplier payment programme across three Asia Pacific markets.
More than 120 suppliers joined the programme. Utilisation of the company’s commercial credit line increased by 100%, buyer DPO increased from 30 to 69 days and supplier DSO reduced from 30 to 15 days. The result shows how the buyer’s payment method can be separated from the supplier’s receipt method: the buyer pays by commercial card through ipaymy, while the supplier receives funds in its bank account.
Results basis
The utilisation, supplier onboarding, DPO and DSO figures reflect the results reported for this customer programme. Results are specific to this implementation and may vary depending on supplier participation, issuer terms, card eligibility, payment timing and programme design.
Customer confidentiality note
Customer details have been generalised to respect confidentiality. The results described are specific to this customer and should not be interpreted as a guarantee of outcomes for other businesses.
Ready to transform your payment operations?

Follow us


